Why the Payment System Is Also a Betting Problem
Most Tanzanian bettors think about their losses in terms of picks — wrong team, bad odds, unlucky result. Very few think about the payment infrastructure sitting underneath every bet they place. But mobile money betting has fundamentally changed not just how funds move, but how decisions get made, how discipline holds or breaks, and how the gap between depositing and withdrawing shapes long-term betting behavior.
This is not about whether M-Pesa or Airtel Money is faster. It is about what happens inside a bettor’s decision-making when the barrier between their mobile wallet and a live betting market is three taps and thirty seconds. That friction — or the near-complete absence of it — has real consequences that most bettors are not accounting for.
How Frictionless Deposits Remove the Pause That Protects Bankroll
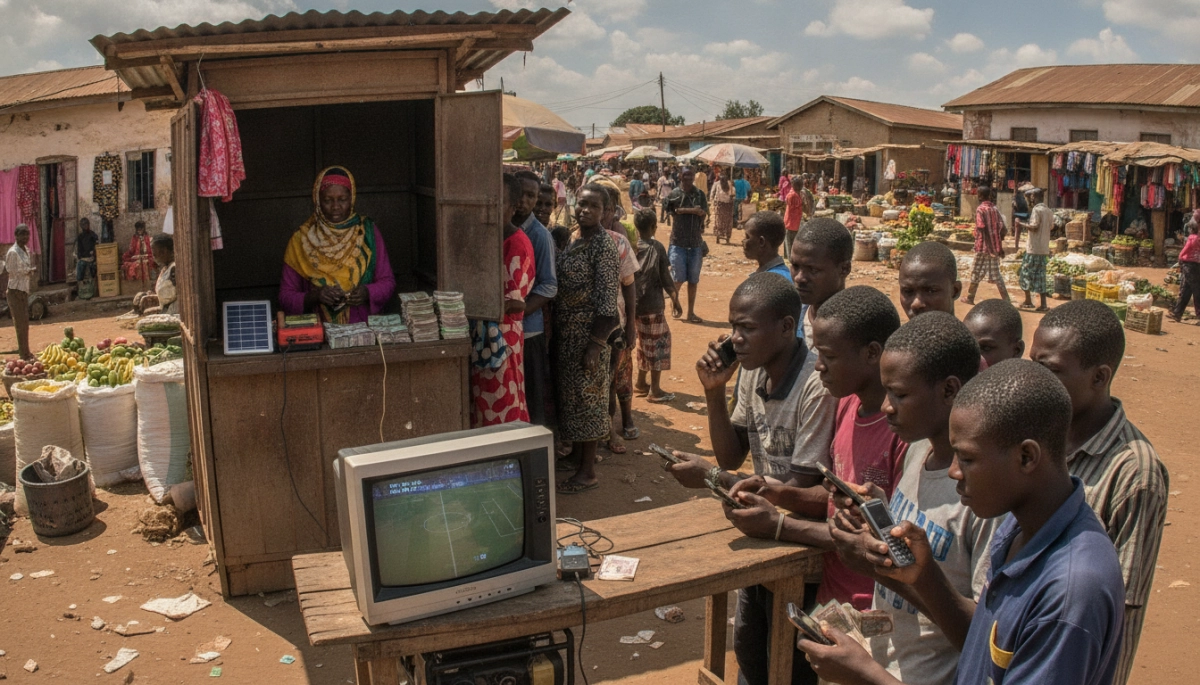
In older betting environments, funding a bet created natural delay. A trip to an agent, a queue, a conversation — all of it slowed impulsive decisions. Mobile money has eliminated almost all of that. Deposits on most Tanzanian platforms confirm within minutes, requiring no more effort than sending a standard mobile payment.
That convenience is useful for a disciplined bettor working within a plan. But it becomes a structural problem the moment emotion enters the picture. After a loss, the time between “I want to recover this” and “the stake is placed” is dangerously short. There is no forced pause, no logistical interruption, nothing that creates space for a second thought.
Experienced bettors who recognize this pattern sometimes create their own artificial friction — moving betting funds to a separate mobile wallet, setting personal deposit intervals, or requiring themselves to log stats before any re-deposit. The point is not to make depositing hard. It is to make impulsive depositing slightly inconvenient enough to interrupt.
Withdrawal Timing and the Psychology of Profit That Stays on Platform
While deposits move fast, withdrawals on many platforms involve processing windows of up to 24 hours. That gap matters more than most bettors acknowledge. When winnings stay visible in a platform balance, a bettor who intended to cash out after a good run can talk themselves into one more bet — often against a balance that technically represents realized profit. Money mentally earmarked as a win gets cycled back into the market before it ever touches their mobile wallet.
The platform balance feels abstract in a way that a wallet balance does not. Understanding that distinction — and treating on-platform funds with the same discipline applied to mobile wallet funds — is where bankroll management either holds or quietly collapses.
How Bet Type and Session Structure Interact With Mobile Money Behavior
The behavioral pressures introduced by mobile money concentrate around specific formats disproportionately popular among Tanzanian football bettors — particularly accumulator betting and live in-play markets. Both interact with instant deposit access in ways that amplify the risks already described.
Accumulator Culture and the Reload Reflex
Accumulator betting dominates Tanzania’s betting landscape for well-documented reasons. Small stakes can theoretically return large amounts, making the format attractive to bettors working with limited bankrolls. But the accumulator’s structure creates near-misses that few other bet types replicate. A bettor can watch five legs land correctly and lose everything on the sixth — one of the strongest emotional triggers for immediate re-staking.
Because a replacement bet can be funded and placed within minutes of the loss, the window for rational evaluation essentially does not exist. The platform surfaces new markets immediately after a settled bet, and mobile money makes acting on them effortless. The combination creates a clear feedback loop: the reload reflex, triggered by a near-miss, executed without friction.
Live Betting and the Compounding Speed Problem
In-play markets compress decision timelines to seconds, with odds fluctuating in real time. The bettor who has already deposited is working from an existing balance, removing even the minor pause a fresh deposit would require. Once money is on the platform, the cost of another bet is purely psychological — there is no mechanical step left to slow anything down.
This is where session length becomes a meaningful variable. Mobile money platforms do not time out, markets run continuously, and a topped-up balance offers no signal that a session should end. Without externally imposed structure, session length defaults to emotional state — the least reliable governor available.
Bettors who manage this successfully tend to share a common habit: they define their session by a bankroll unit rather than a time window or result target. When a fixed number of units is gone, the session is over. That approach translates directly into deposit behavior — funding the account with exactly what the session requires, rather than loading a larger buffer that creates the illusion of flexibility.
The Real Cost of Treating Mobile Money as a Neutral Tool
There is a persistent assumption among bettors that payment infrastructure is background utility — a neutral pipe through which decisions flow. The argument here is that this framing is incorrect, and accepting it is itself a behavioral risk.
How Platform Balances Distort Perceived Bankroll Size
When bettors fund their accounts through mobile money, the funds shift from a wallet they interact with daily to a platform balance viewed through a dedicated app. That context shift changes how the money is perceived — closer to a gaming credit than a real-world financial asset — and affects how freely bettors stake against it.
This connects to a documented mechanism sometimes called the house money effect, where funds that have been won or mentally reclassified are treated with less caution than original capital. In Tanzania’s mobile money context, even deposited funds can shift into this category quickly after an early win. The bettor who deposited 10,000 shillings and built it to 15,000 often stakes the full balance with the aggression appropriate to 5,000 — because the original deposit feels recovered regardless of outcome.
Correcting for this requires treating a platform balance with exactly the same discipline as a mobile wallet balance, applying the same staking percentages and loss limits regardless of how the balance was built. The behavioral gap between knowing that principle and executing it under live conditions is where most bankroll structures quietly fail.
Building Discipline Into a System Designed to Remove It
The honest conclusion is that Tanzania’s mobile money betting environment is structurally optimized for volume, not for the bettor’s long-term financial health. That is a practical observation about incentive alignment — and recognizing it clearly is the first requirement for operating within the system without being shaped by it.
Discipline here cannot be passive. A bettor relying on willpower alone to manage session length, deposit frequency, and withdrawal timing is competing against infrastructure specifically designed to reduce all three forms of friction. The player who wins that competition consistently is almost always the one who has externalized their rules — written them down, structured deposits in advance, and treated the withdrawal request as the final act of every session rather than an afterthought.
Practically, this means several habits that operate before the betting starts. Depositing only what a session plan calls for, rather than a round number that leaves a surplus. Initiating withdrawals immediately when a target is reached, so funds are psychologically committed to leaving the platform. Logging each deposit as a transaction with a recorded purpose, which creates exactly the kind of reflective pause that mobile money’s speed removes by default. For bettors seeking a reference framework, resources like those published by the Responsible Gambling Council offer evidence-based models that apply regardless of payment method.
Mobile money made betting in Tanzania more accessible than it has ever been. That accessibility is genuinely valuable for bettors who approach it with structure. It is genuinely dangerous for those who treat the payment layer as invisible. The difference between those two groups is not luck, talent, or knowledge of football. It is whether they have taken the behavioral consequences of instant, frictionless funding seriously enough to build a system that accounts for them — before the next match kicks off and the next deposit prompt appears on their screen.