Why the “2% of your bankroll” rule breaks down in Tanzania
Most staking advice circulating online was written for someone with a bank account, a fixed monthly salary, and instant access to their full balance. That person does not describe most bettors placing wagers through mobile money in Dar es Salaam, Mwanza, or Arusha. Sports betting Tanzania operates on a different financial rhythm, and pretending otherwise is part of why so many serious bettors keep losing ground even when their picks are decent.
The standard advice says stake 1-2% of your bankroll per bet and adjust as that bankroll grows or shrinks. It sounds disciplined on paper. In practice, it assumes your bankroll is a static number sitting untouched in an account, rather than money that moves through M-Pesa, Tigo Pesa, or Airtel Money and gets taxed every time it moves.
The transaction cost problem generic staking guides ignore
Every deposit and withdrawal through mobile money carries a fee. Vodacom’s M-Pesa charges roughly TSh25 per transfer and around TSh80 per withdrawal, and while that sounds small on a single transaction, it adds up fast for a bettor topping up their account three or four times a week to chase a 2% unit size that keeps shifting.
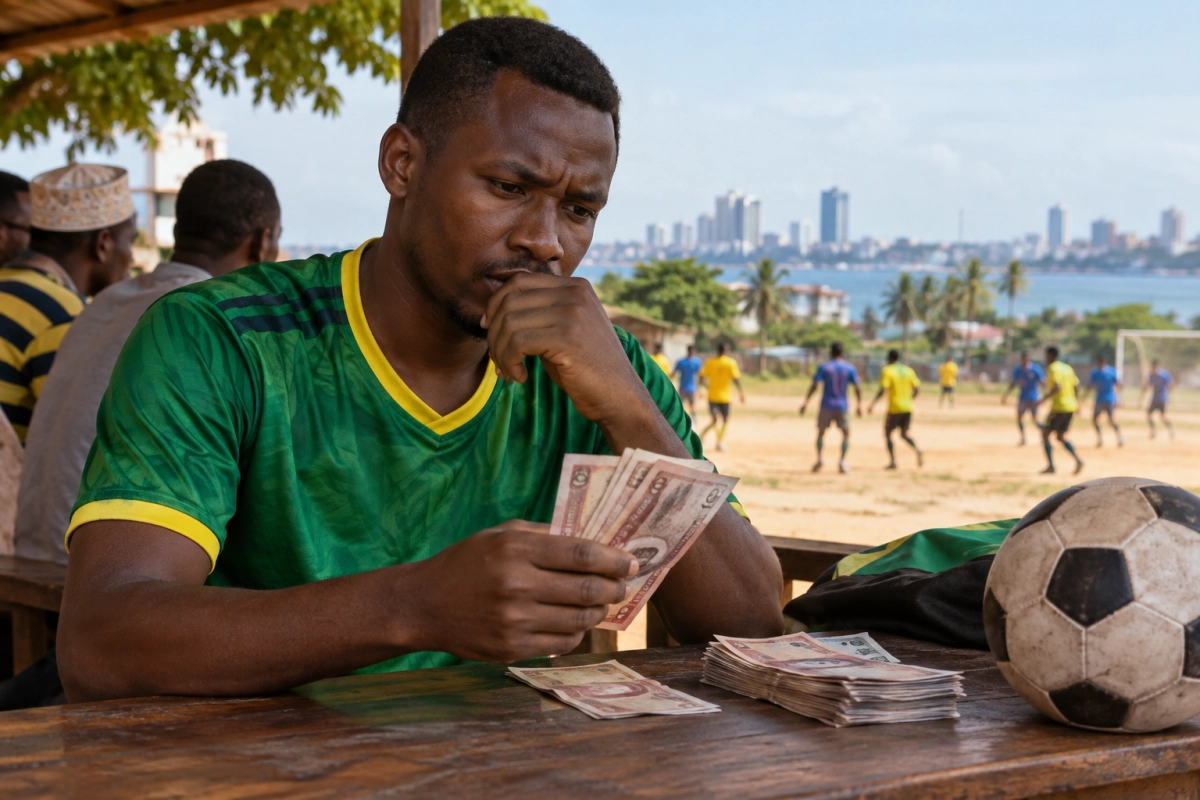
A bettor working with a 50,000 TZS bankroll who tries to stake exactly 2% per bet is placing 1,000 TZS wagers, then topping up in small increments every time the balance dips. Each top-up eats into the bankroll before the bet is even placed. The math that looks clean in a spreadsheet gets eroded by real transaction friction that European staking guides never had to account for.
Irregular income cycles make fixed percentages meaningless
Percentage-based staking assumes a bettor can replenish their bankroll on a predictable schedule. For bettors working informal jobs, running small businesses, or getting paid in cash at irregular intervals, that assumption falls apart quickly. A bankroll might jump from 20,000 TZS to 150,000 TZS after a good week of income, then sit untouched for ten days.
Recalculating 1-2% every time that number changes turns bankroll management into a moving target rather than a stable system. Bettors end up either understaking during flush periods, leaving real value on the table, or overstaking during lean weeks because the percentage felt too small to bother with.
None of this means percentage-based thinking is useless. It means the percentage needs to be anchored to something more stable than a bankroll that fluctuates with cash flow, mobile money fees, and withdrawal timing all at once. The next question is what that more stable anchor actually looks like, and how tiered withdrawal limits and agent levies factor into building it.
Building a stake unit around withdrawal tiers instead of bankroll percentage
Mobile money withdrawal limits are not a footnote in this discussion, they are one of the core constraints that should shape how a Tanzanian bettor thinks about stake size in the first place. M-Pesa, Tigo Pesa, and Airtel Money all operate tiered withdrawal structures where the fee percentage improves at higher brackets, which means small, frequent withdrawals are quietly more expensive per shilling than fewer, larger ones. A bettor who cashes out winnings in dribs and drabs is paying a hidden tax that never shows up in a staking spreadsheet but shows up clearly in a monthly total.
This is why the more useful anchor isn’t a percentage of bankroll but a fixed stake unit calibrated against the withdrawal bracket a bettor actually operates in. If someone regularly moves money in the 40,000-100,000 TZS range, their stake unit should be set so that a full session of betting, win or lose, produces balances that land cleanly within that bracket rather than spilling just over it and triggering a worse fee tier on the way out. Practically, that might mean rounding a stake down from 1,800 TZS to 1,500 TZS not because the percentage math says so, but because it keeps end-of-week balances inside a cheaper withdrawal band.
Agent levies add another layer most guides skip entirely. Cashing in or out through a physical agent, common in areas with patchy network access or for bettors who prefer not to leave winnings sitting in a wallet, often carries an informal float charge on top of the network’s official fee. A stake unit that ignores this compounds the cost twice over: once on the deposit that funded the bet, and again on the withdrawal that followed it.
Separating betting capital from working capital
One habit that quietly wrecks disciplined staking is keeping betting money and everyday spending money in the same mobile wallet. When a bettor’s entire financial life runs through one M-Pesa balance, every bet placed is measured against a number that also includes rent money, business float, or family obligations, which makes any stake size feel simultaneously too big and too small depending on the day.
A cleaner approach treats the betting bankroll as a ring-fenced sub-account, even if the platform doesn’t offer that feature natively. This can mean moving a fixed amount into a separate wallet or SIM specifically for betting once income arrives, then never topping it up mid-week regardless of how tempting a fixture looks. The transaction fee for that one transfer is a cost worth paying, because it buys clarity that no percentage formula can substitute for.
This separation also solves the recalculation problem raised earlier. Instead of adjusting stake size every time overall cash flow shifts, the bettor adjusts it only when they consciously decide to fund the betting sub-account, which happens on their schedule, not the bankroll’s.
Sizing stakes around bet settlement speed, not just amount
Odds and outcomes settle at different speeds depending on market type, and that speed interacts directly with mobile money costs. A bettor cycling through several small in-play bets in one evening triggers multiple potential withdrawal-and-redeposit cycles if they’re chasing losses, each one shaving value off through fees. Structuring stakes around slower-settling markets, single pre-match bets rather than a string of live wagers, reduces how often money needs to move at all.
This isn’t about avoiding in-play markets altogether, it’s about recognizing that every settlement is a potential trigger for another mobile money transaction, and each of those transactions has a cost that a purely odds-based strategy will never account for. A stake unit built with settlement speed in mind ends up doing double duty: it manages risk the way any staking plan should, while also minimizing the number of times money has to pass through a network that charges for the privilege of moving it.
Discipline That Fits the Wallet You Actually Have
Bankroll management was never meant to be a universal formula, it’s a reflection of the financial system a bettor actually operates within. For someone betting through mobile money in Tanzania, that system includes tiered fees, agent levies, irregular income, and withdrawal brackets that reward patience over frequency. A staking plan that ignores those realities isn’t more disciplined for following a clean percentage, it’s simply less accurate.
The bettors who protect their bankroll longest are rarely the ones with the most complex formula. They’re the ones who’ve built a stake unit around their own cash flow rhythm, ring-fenced their betting money from everyday spending, and structured their withdrawals to avoid paying twice for the same shilling. None of that requires abandoning the principles behind responsible staking, outlined well by resources like BeGambleAware, it just requires applying them to the wallet you actually have, not the bank account the advice assumed you’d have.
Get that anchor right, and the rest of the strategy, odds selection, market timing, discipline under losing streaks, finally has something stable to stand on.